GOLDEN ENERGY FZ | Market Intelligence | Updated 2 November 2026
Executive summary: Saudi Arabia’s September 2026 crude-pricing reductions initially offered European refiners a more competitive formula for medium-sour oil. Yet a disruption to the kingdom’s East–West pipeline and elevated maritime costs turned the original discount story into a question of physical availability. By November, Aramco’s Arab Light official selling price (OSP) differential for Northwest Europe and the Mediterranean had risen by US$3 per barrel compared with September. For buyers, the key distinction is between the quoted benchmark differential and the actual landed economics of a refinery-ready cargo.
1. The original Argus signal: why Saudi oil looked attractive
On 17 August 2026, Argus Media published a podcast examining how Saudi Aramco’s larger-than-expected reductions to official selling prices could help European buyers sourcing medium-sour crude for September. European refiners were seeking alternatives as the Middle East conflict altered their traditional procurement routes. The analysis focused on the relative competitiveness of Saudi term barrels, Iraqi SOMO pricing and spot-market substitutes, alongside logistical risks affecting the Strait of Hormuz, the Red Sea and Saudi Arabia’s western export corridor.
An OSP is not the full price of a barrel: it is a formula adjustment applied to a reference benchmark for a specified delivery market and pricing window. A discount is attractive only if crude quality, delivery certainty, vessel costs and refinery yields remain workable.
2. September versus November: the pricing reversal
Argaam’s published Saudi Aramco pricing schedules show September 2026 Arab Light at US$2.15/bbl below ICE Brent for Northwest Europe and US$2.35/bbl below ICE Brent for the Mediterranean. The corresponding November formula differentials reached US$0.85/bbl above ICE Brent and US$0.65/bbl above ICE Brent, respectively.
| Arab Light destination | September 2026 OSP | November 2026 OSP | Change |
|---|---|---|---|
| Northwest Europe | ICE Brent − $2.15/bbl | ICE Brent + $0.85/bbl | +$3.00/bbl |
| Mediterranean Europe | ICE Brent − $2.35/bbl | ICE Brent + $0.65/bbl | +$3.00/bbl |
Source: Argaam’s reports on the Aramco September and November OSP schedules. These are benchmark differentials, not outright crude prices. The benchmark level and final delivered cost can differ between the two periods.
For illustration, a US$3/bbl change in the formula differential across a 1-million-barrel cargo is equivalent to US$3 million before accounting for the benchmark movement, freight, insurance, finance or quality adjustments. This is an illustration of pricing sensitivity, not an assertion that each refinery’s invoice rose by that amount.
3. The supply-chain bottleneck: the East–West pipeline and Yanbu
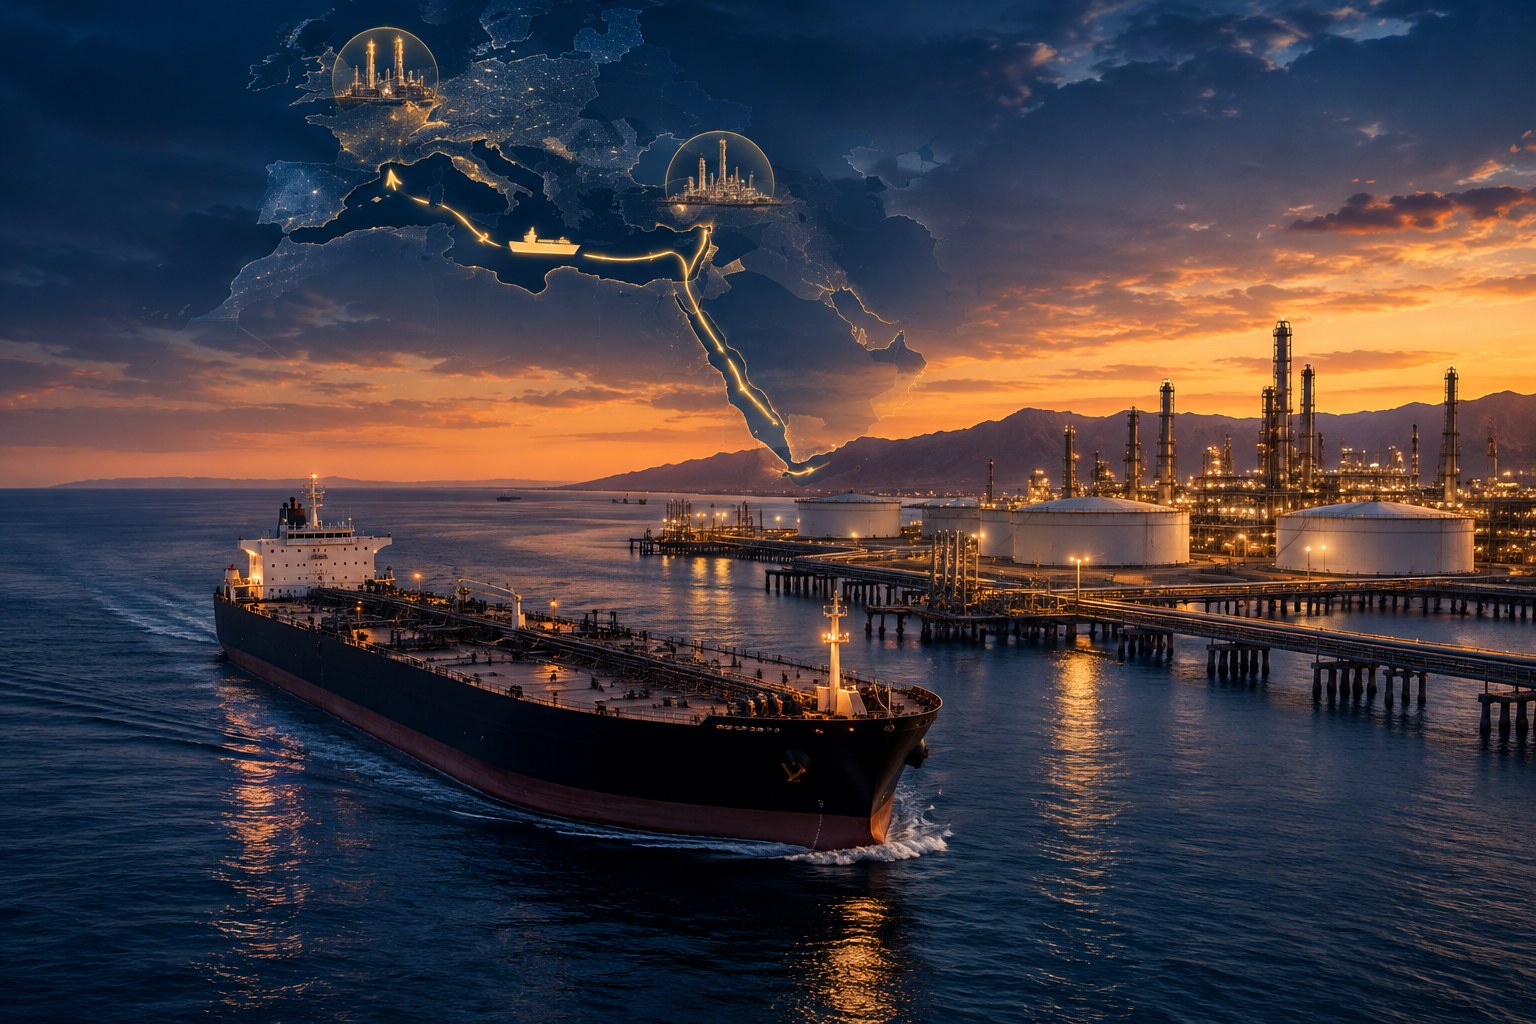
Saudi Arabia’s East–West pipeline provides a strategic route to the Red Sea loading system at Yanbu, allowing some westbound oil to bypass voyages through the Strait of Hormuz. Cargoes may reach Mediterranean buyers through Suez-related infrastructure, including the SUMED corridor and Sidi Kerir where appropriate. The utility of this route depends on pipeline throughput, terminal operations, available storage, vessel scheduling and maritime security.
In September, attacks affecting the East–West pipeline disrupted crude movements and caused the postponement or cancellation of some deliveries to European refiners, according to industry reporting. The disruption should not be interpreted as a blanket cancellation of all Saudi export commitments. By the end of September, reports described the resumption of crude loading activity around Yanbu after the pipeline restart. Recovery of terminal operations does not automatically eliminate cargo backlogs or chartering constraints.
4. October market evidence: recovery, but at a high cost
The International Energy Agency’s Oil Market Report of 14 October 2026 estimated Gulf crude exports at 13.9 million barrels per day in September, more than 75% of their pre-war level, as supply recovered and bypass flows expanded. However, the IEA warned that renewed security incidents could interrupt the rebound.
The same report cited an average US$116.89/bbl for North Sea Dated in September, an increase of US$26.17/bbl month on month, while record tanker costs and higher crude prices weakened margins for refiners in Europe and Asia. September global diesel/gasoil exports were approximately 700,000 barrels per day below the year-earlier level. These are reported historical observations, not live November market prices.
Late-October reporting indicated that Aramco offered additional spot cargoes for European buyers from Yanbu or Sidi Kerir for October and November loading, with November term allocations expected to improve. Spot offers and expected allocations remain subject to scheduling and execution; buyers should independently verify cargo nominations and contractual commitments.
5. Why crude quality matters as much as headline price
Not all crude grades are interchangeable. Arab Light is commonly classified as a medium-sour oil, but each refinery has its own distillation, hydrotreating, sulphur-removal, residue-upgrading and blending constraints. Substituting an Iraqi, North Sea, Caspian or Atlantic Basin grade requires an assay-based comparison of API gravity, sulphur, metals, viscosity and the product slate. A nominally cheaper cargo may yield less saleable diesel or generate higher processing costs.
The proper comparison is quality-adjusted netback or refinery-gate economics, not simply the lowest quoted OSP. This becomes especially important when freight, voyage duration, payment terms and marine insurance vary widely by origin.
6. Implications for diesel, fuel oil, bunkers and bitumen
Diesel and middle distillates
Restricted diesel availability can widen product cracks, but stronger product revenue does not guarantee stronger refining margins when crude and logistics costs are also surging. Buyers should compare physical diesel benchmarks and sulphur specifications independently of crude OSP movements.
HSFO 380 and marine fuels
Crude-slate changes affect the volume and quality of refinery residues used in high-sulphur fuel-oil blending. Bunker prices also depend on port inventories, local blendstocks, marine fuel compliance requirements and vessel availability. A US$3/bbl crude OSP adjustment does not translate directly into a US$3/bbl move in HSFO or marine gasoil.
Bitumen and other petroleum products
Bitumen production depends on residue characteristics and refinery configuration. Base oils and other specialty products have their own production pathways, specification premiums and regional market balances. For physical traders, the practical response to upstream disruption is to reassess feedstock costs, delivery windows, supply alternatives and working-capital exposure—not to apply a uniform price forecast across unrelated products.
7. Contract execution: a practical checklist for buyers
- Price formula: confirm the benchmark, pricing window, OSP differential, destination, currency and quality adjustments.
- Product compatibility: review crude assay and expected refinery yields, not just the grade name.
- Logistics: verify loading port, availability, nomination, voyage route, terminal slots, laycan and discharge constraints.
- Landed cost: incorporate freight, insurance, financing, inspection, storage, demurrage and foreseeable delays.
- Counterparty controls: confirm sanctions compliance, documents, ship eligibility, surveyor arrangements and agreed payment terms.
Working model: Estimated landed crude cost = reference benchmark + contractual differential and quality adjustments + freight and insurance + financing and anticipated execution expenses. Refinery decision-makers must then compare this cost against the expected product yield and netback.
8. Three scenarios for the remainder of 2026
Base case — uneven normalization: western export routes continue functioning and more Saudi barrels reach European refiners, but freight volatility and physical execution risks remain material.
Disruption case — renewed bottlenecks: fresh infrastructure or maritime incidents restrict medium-sour availability, lift replacement costs and pressure margins even where diesel prices remain elevated.
Demand case — lower refinery intake: expensive crude and softening consumption reduce refinery runs and crude demand, while weaker throughput may also reduce local availability of finished products.
These are decision-making scenarios rather than guaranteed forecasts.
9. Golden Energy market perspective
For Golden Energy FZ, the central lesson is that market intelligence must be integrated with practical trade execution. Buyers, brokers and suppliers of petroleum products should monitor crude quality, Saudi and Iraqi formula-price differentials, diesel cracks, freight economics, vessel movements, product availability and contractual documentary risk together.
This report is Golden Energy’s independent market commentary, drawing on cited third-party publications. It is intended for informational purposes and does not constitute a price quotation, cargo-availability confirmation, investment recommendation or binding offer.
Related Golden Energy market intelligence
- Diesel supply tightness, Strait of Hormuz risks and LNG markets
- Earlier oil-market outlook and EIA price expectations
- Golden Energy petroleum products portfolio
Sources and editorial notes
- Argus Media — Saudi crude September OSP cut for Europe (17 August 2026)
- Argaam — Saudi Aramco September official selling prices (6 August 2026)
- Argaam — Saudi Aramco November official selling prices (October 2026)
- IEA — Oil Market Report, October 2026 (14 October 2026)
- Reuters — Aramco November price adjustments for regional markets (October 2026)
- OilPrice.com — Aramco’s additional European spot offers, citing Bloomberg (27 October 2026)
Editorial date: 2 November 2026. The original Argus article discusses expectations for September; this independently written Golden Energy analysis incorporates later reported events through late October. Official pricing differentials are distinct from total delivered crude prices.