Golden Energy Market Intelligence — 3 October 2026
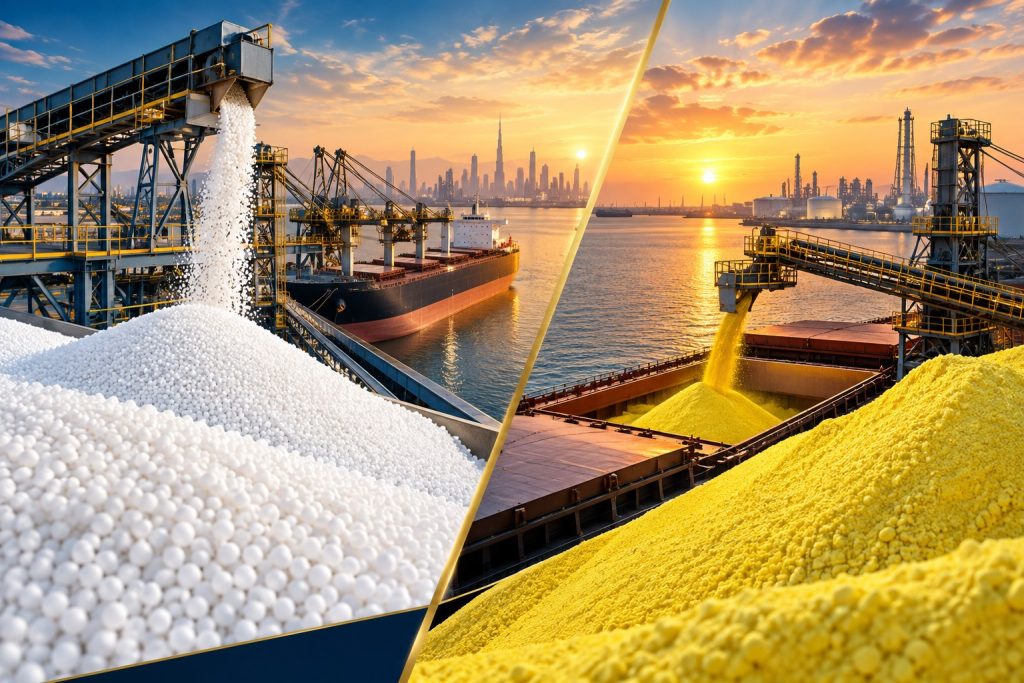
Middle East fertilizer and sulfur markets entered October with a clear divergence: granular urea remains comparatively firm after a strong September, while regional granular sulfur prices have moved lower from late-September levels. For buyers and traders, the difference is becoming increasingly important for timing purchases, negotiating FOB values and managing freight exposure.
Granular urea holds near USD 445/MT FOB Middle East
Indicative assessments for Middle East granular urea were around USD 445/MT FOB on 2 October 2026. The market had reached about USD 465/MT in late September before easing back toward current levels. The October opening therefore shows a softer tone compared with the final week of September, but values remain above much of August.
Prilled urea has also softened. Argus-linked market data for 1 October indicated FOB Middle East prilled urea at USD 430–450/MT, compared with USD 445–460/MT one week earlier.
For regional suppliers, the market remains sensitive to export availability, destination demand and freight economics. Earlier this year, disruptions around the Strait of Hormuz demonstrated how quickly fertilizer prices can react to shipping constraints. Reuters reported that before the 2026 conflict, roughly one-third of globally traded urea normally moved through the strait, underlining the strategic importance of Gulf logistics to global fertilizer supply.
Granular sulfur corrects from late-September highs
The sulfur market is showing a sharper adjustment. Argus-linked assessments for 1 October placed FOB Middle East sulfur excluding Iran at USD 810–850/MT, down from USD 860–890/MT on 24 September. At the same time, CFR China granular sulfur remained around USD 960–970/MT, indicating that delivered Asian values have held firmer than Middle East FOB indications.
Qatar’s October sulfur selling price was reported at USD 835/MT FOB. The combination of softer regional FOB levels and firmer downstream values suggests that freight, cargo timing and origin are playing a major role in determining executable economics.
Pricing methodology is also changing
S&P Global Platts discontinued its quarterly FOB Middle East contract sulfur assessment on 25 September 2026 following market feedback and changes in contractual pricing practices. Platts continues to publish spot granular sulfur assessments for the Middle East. For traders, this increases the importance of understanding the exact benchmark, delivery basis and pricing methodology referenced in each contract.
Golden Energy view
Urea is beginning October in a relatively balanced but still firm range, while sulfur is undergoing a more visible regional correction. Buyers should avoid treating headline prices as directly comparable across origins: parcel size, FOB versus CFR basis, port restrictions, freight and loading windows can materially change the final landed cost.
Golden Energy FZ continues to monitor executable opportunities in granular urea, prilled urea and granular sulfur across the Middle East, South Asia and other key destination markets.
Market references: CommodityScope assessments dated 2 October 2026; Argus-linked market tables dated 1 October 2026; S&P Global Platts methodology notice dated 25 September 2026; Reuters fertilizer trade-flow reporting.
This market update is for informational purposes only and does not constitute a binding offer or price quotation.